Best DeFi Yields on Ethereum After Devcon 8 — November 2026
The best DeFi yields available on Ethereum and its L2s after Devcon 8 in November 2026. Aave v3, Curve, Pendle, and restaking rates with honest risk comparison.


Devcon 8 (November 3–6) is the event most likely to shift yield dynamics in the Ethereum DeFi ecosystem in Q4 2026. New protocol announcements, roadmap updates that affect liquidity incentive structures, and the general sentiment bump to Ethereum activity all affect available yields in the weeks following the event.
This article covers the best available DeFi yields on Ethereum as of October 2026, with Devcon 8 context for each category.
Current yield landscape: October 2026 baseline
| Protocol | Asset | APY range | Type | Risk |
|---|---|---|---|---|
| Aave v3 (Base) | USDC | 5.8–7.2% | Variable lending | Low |
| Aave v3 (Ethereum) | USDC | 4.2–5.6% | Variable lending | Low |
| Curve 3pool | 3CRV | 3.1–4.4% | Stablecoin AMM | Low |
| Convex Finance | CVX-boosted Curve | 5.8–8.2% | Boosted Curve LP | Low-medium |
| Pendle (PT-stETH Q1 27) | stETH | 4.1–4.8% fixed | Fixed yield | Medium |
| EigenLayer restaking | stETH | 6.2–8.4% | Restaking | Medium-high |
| Morpho Blue | USDC | 6.1–8.9% | Optimized lending | Medium |
| Ethena (sUSDe) | USDC | 8.2–14% | Funding rate synthetic | High |
All rates from public protocol dashboards as of late October 2026. Rates change continuously.
Aave v3: the institutional-grade benchmark
Aave v3 across Ethereum and its primary L2 deployments (Base, Arbitrum, Optimism) represents the most widely trusted DeFi lending infrastructure. Supply rates for USDC on Aave v3 have been 4–7% through Q3 2026, driven by borrower demand for stablecoin leverage.
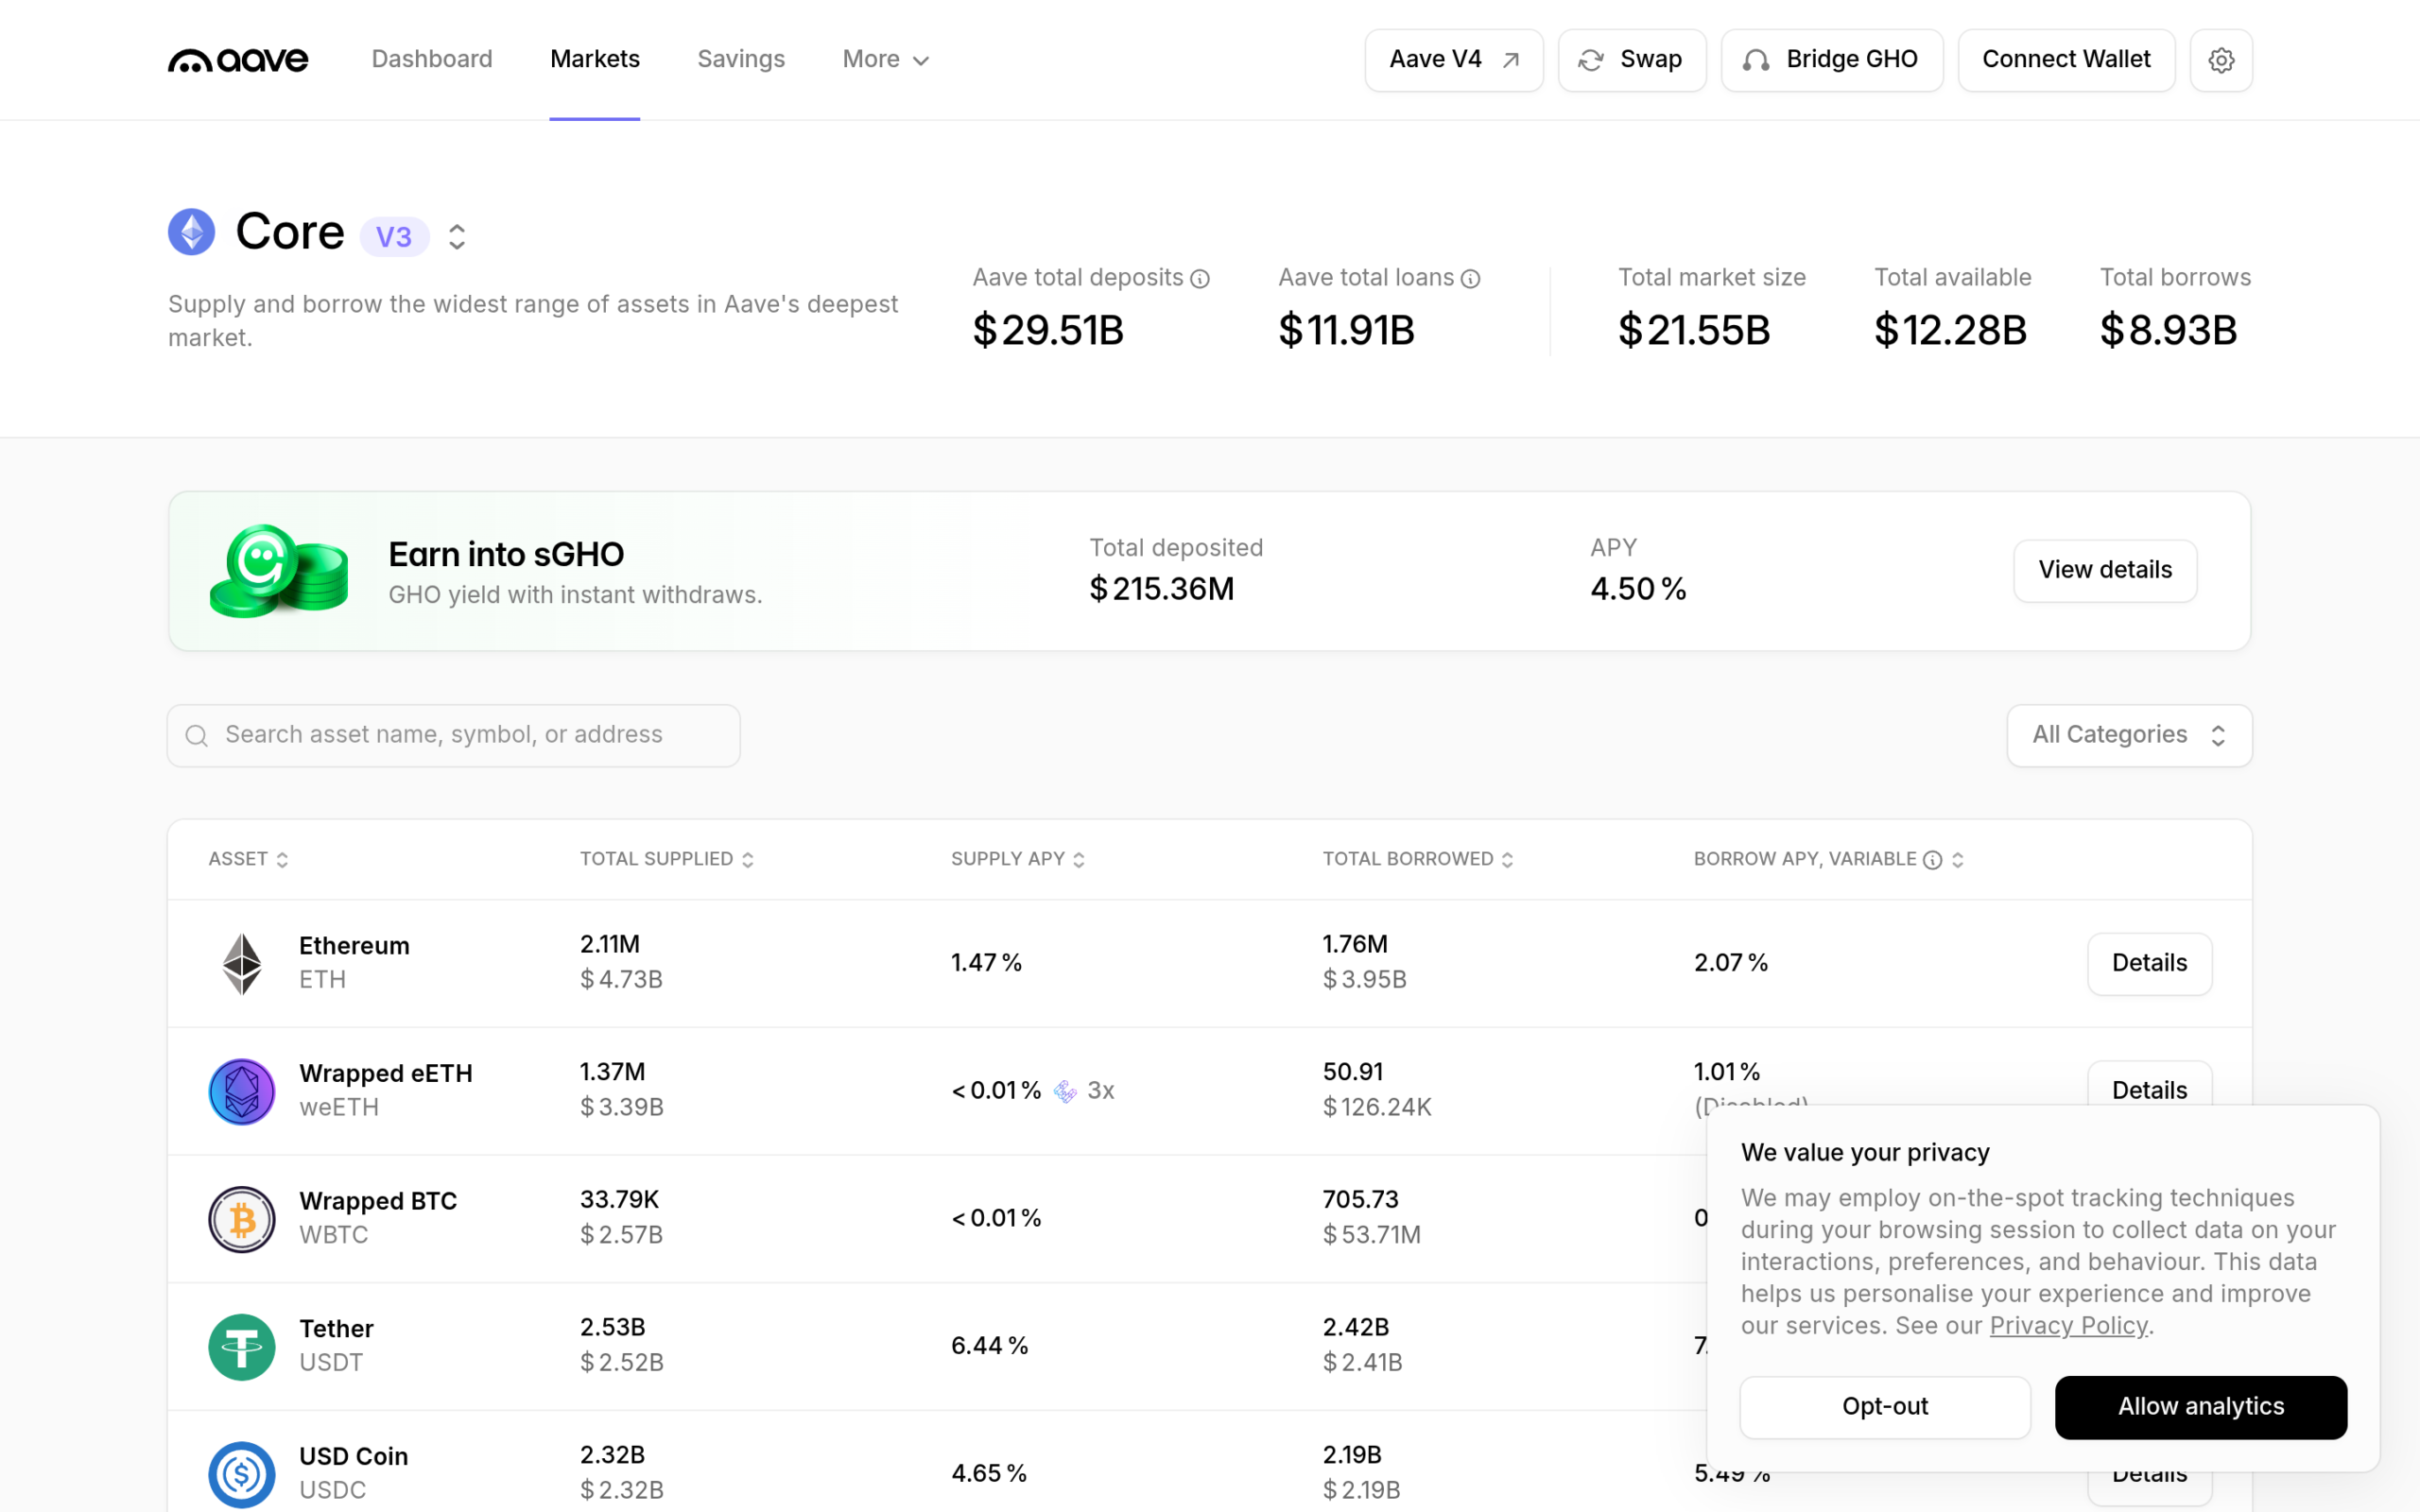
Why Devcon 8 matters for Aave: Aave’s v4 roadmap — which includes a unified liquidity layer across chains, a new cross-chain GHO stablecoin architecture, and “smart accounts” for simplified position management — is expected to receive technical detail at Devcon 8. Positive roadmap signals typically accelerate TVL growth, which increases borrower demand and supply yields.
Honest caveat: Aave v3 rates on Ethereum mainnet have compressed below Base and Arbitrum deployments because mainnet gas costs deter smaller borrowers, reducing aggregate demand. If you are optimizing for yield, Aave v3 on Base or Arbitrum typically offers higher rates for the same risk profile.
Curve and Convex: stablecoin liquidity infrastructure
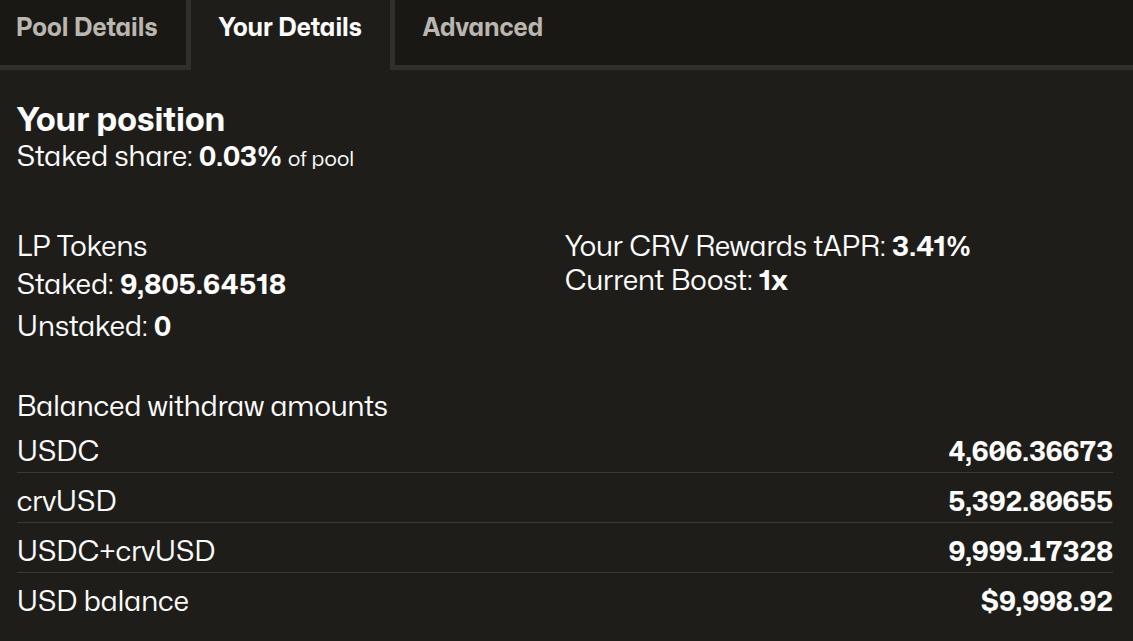
Curve Finance remains the primary venue for stablecoin and correlated-asset liquidity on Ethereum. The 3pool (USDT/USDC/DAI) offers 3.1–4.4% from trading fees alone. Convex Finance amplifies Curve yields by pooling veCRV voting power — depositing Curve LP tokens into Convex typically adds 2–4% on top of base Curve rates.
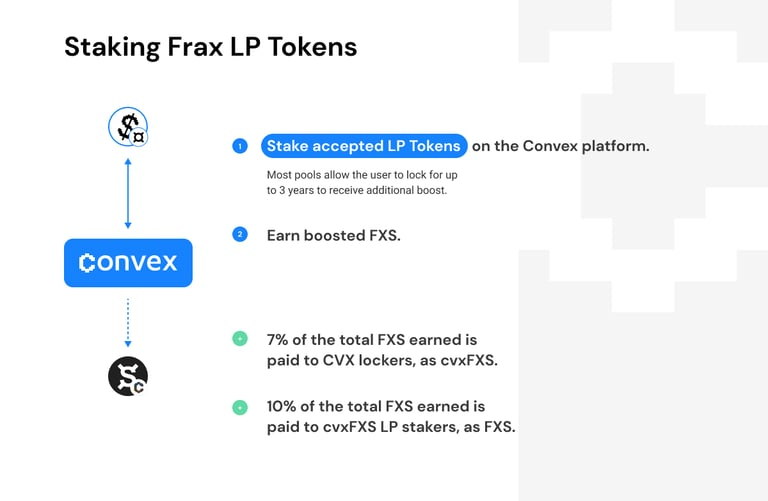
Current effective Convex yields for stable pools: 5.8–8.2% APY combining base fees, CRV emissions, and CVX rewards.
Post-Devcon outlook: Curve’s crvUSD stablecoin (launched 2023) has grown steadily and now represents a material portion of Curve revenue. Devcon 8 sessions on stablecoin infrastructure and cross-chain liquidity are directly relevant to crvUSD expansion plans. Positive sessions could accelerate crvUSD adoption and increase Curve fee revenue.
Pendle Finance: lock in fixed yield before year-end
Pendle allows users to split yield-bearing tokens (stETH, aUSDC, sUSDe) into Principal Tokens (PT, which trade at a discount to face value) and Yield Tokens (YT, which capture all future yield). Buying PT locks in a known fixed return at maturity.
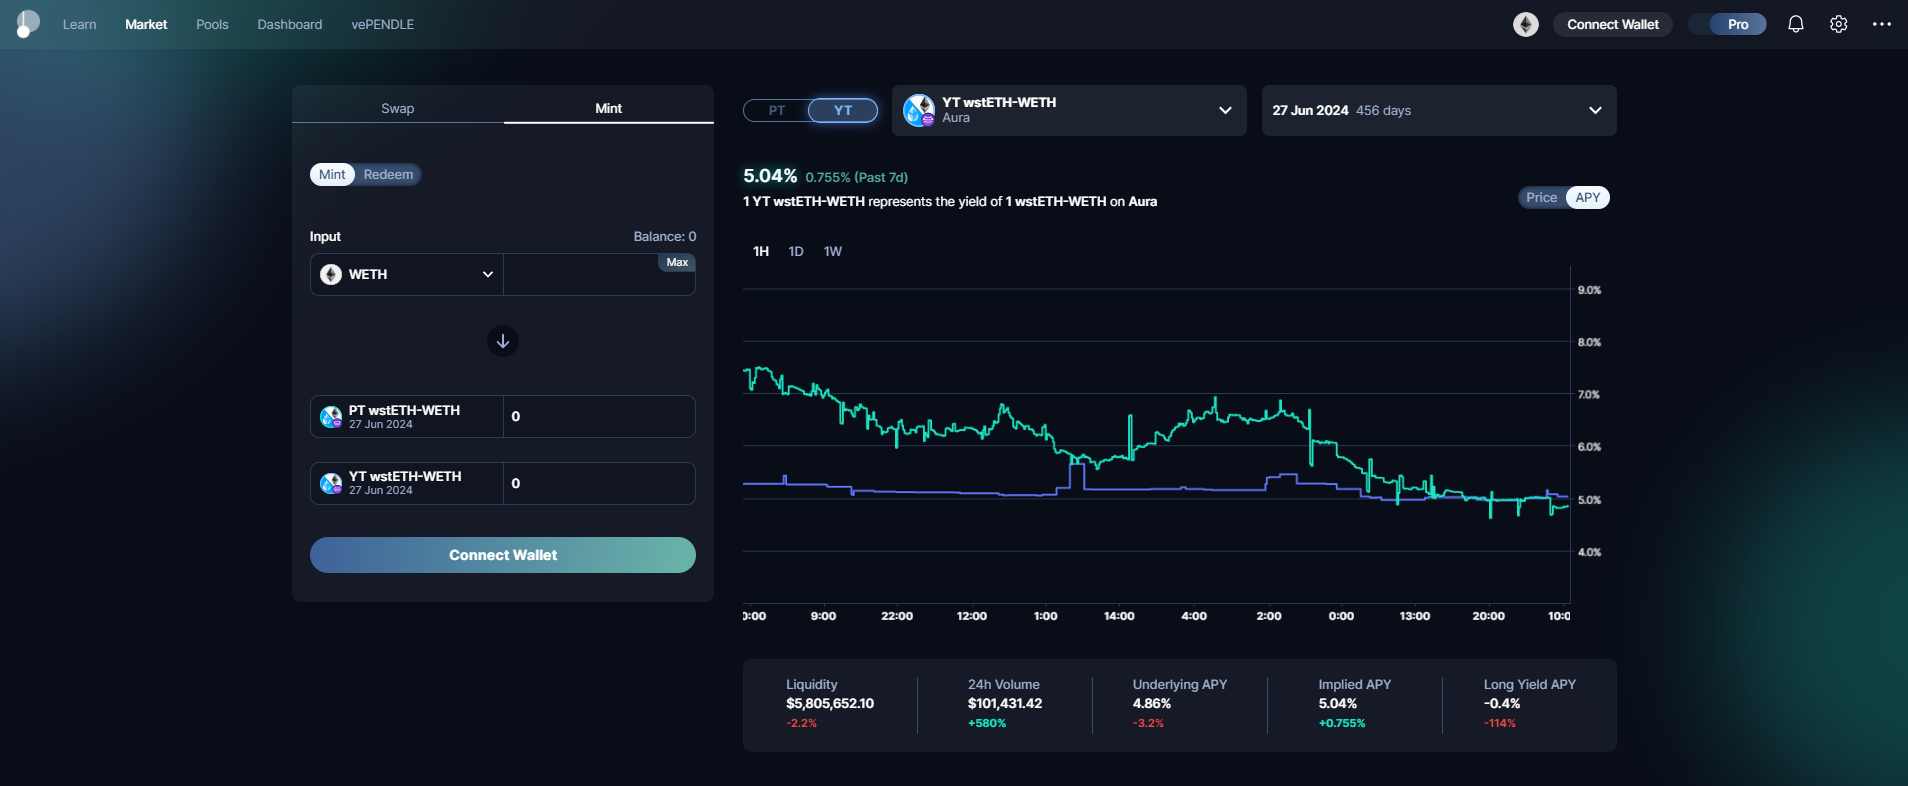
November 2026 fixed yields available on Pendle:
- PT-stETH (matures March 2027): ~4.5% fixed annualized
- PT-aUSDC-Base (matures January 2027): ~5.1% fixed annualized
- PT-sUSDe (matures February 2027): ~9.2% fixed annualized (with Ethena risk embedded)
Year-end tax angle: Locking in a fixed PT position before December 31 creates predictable income for the 2026 tax year. Variable yield positions have unpredictable income recognition timing.
Morpho Blue: optimized lending rates
Morpho Blue is a lending protocol designed to optimize rates between suppliers and borrowers by reducing the spread that pooled lending models require. Instead of a shared pool with a single rate curve, Morpho Blue creates isolated markets for specific collateral/borrow asset pairs.
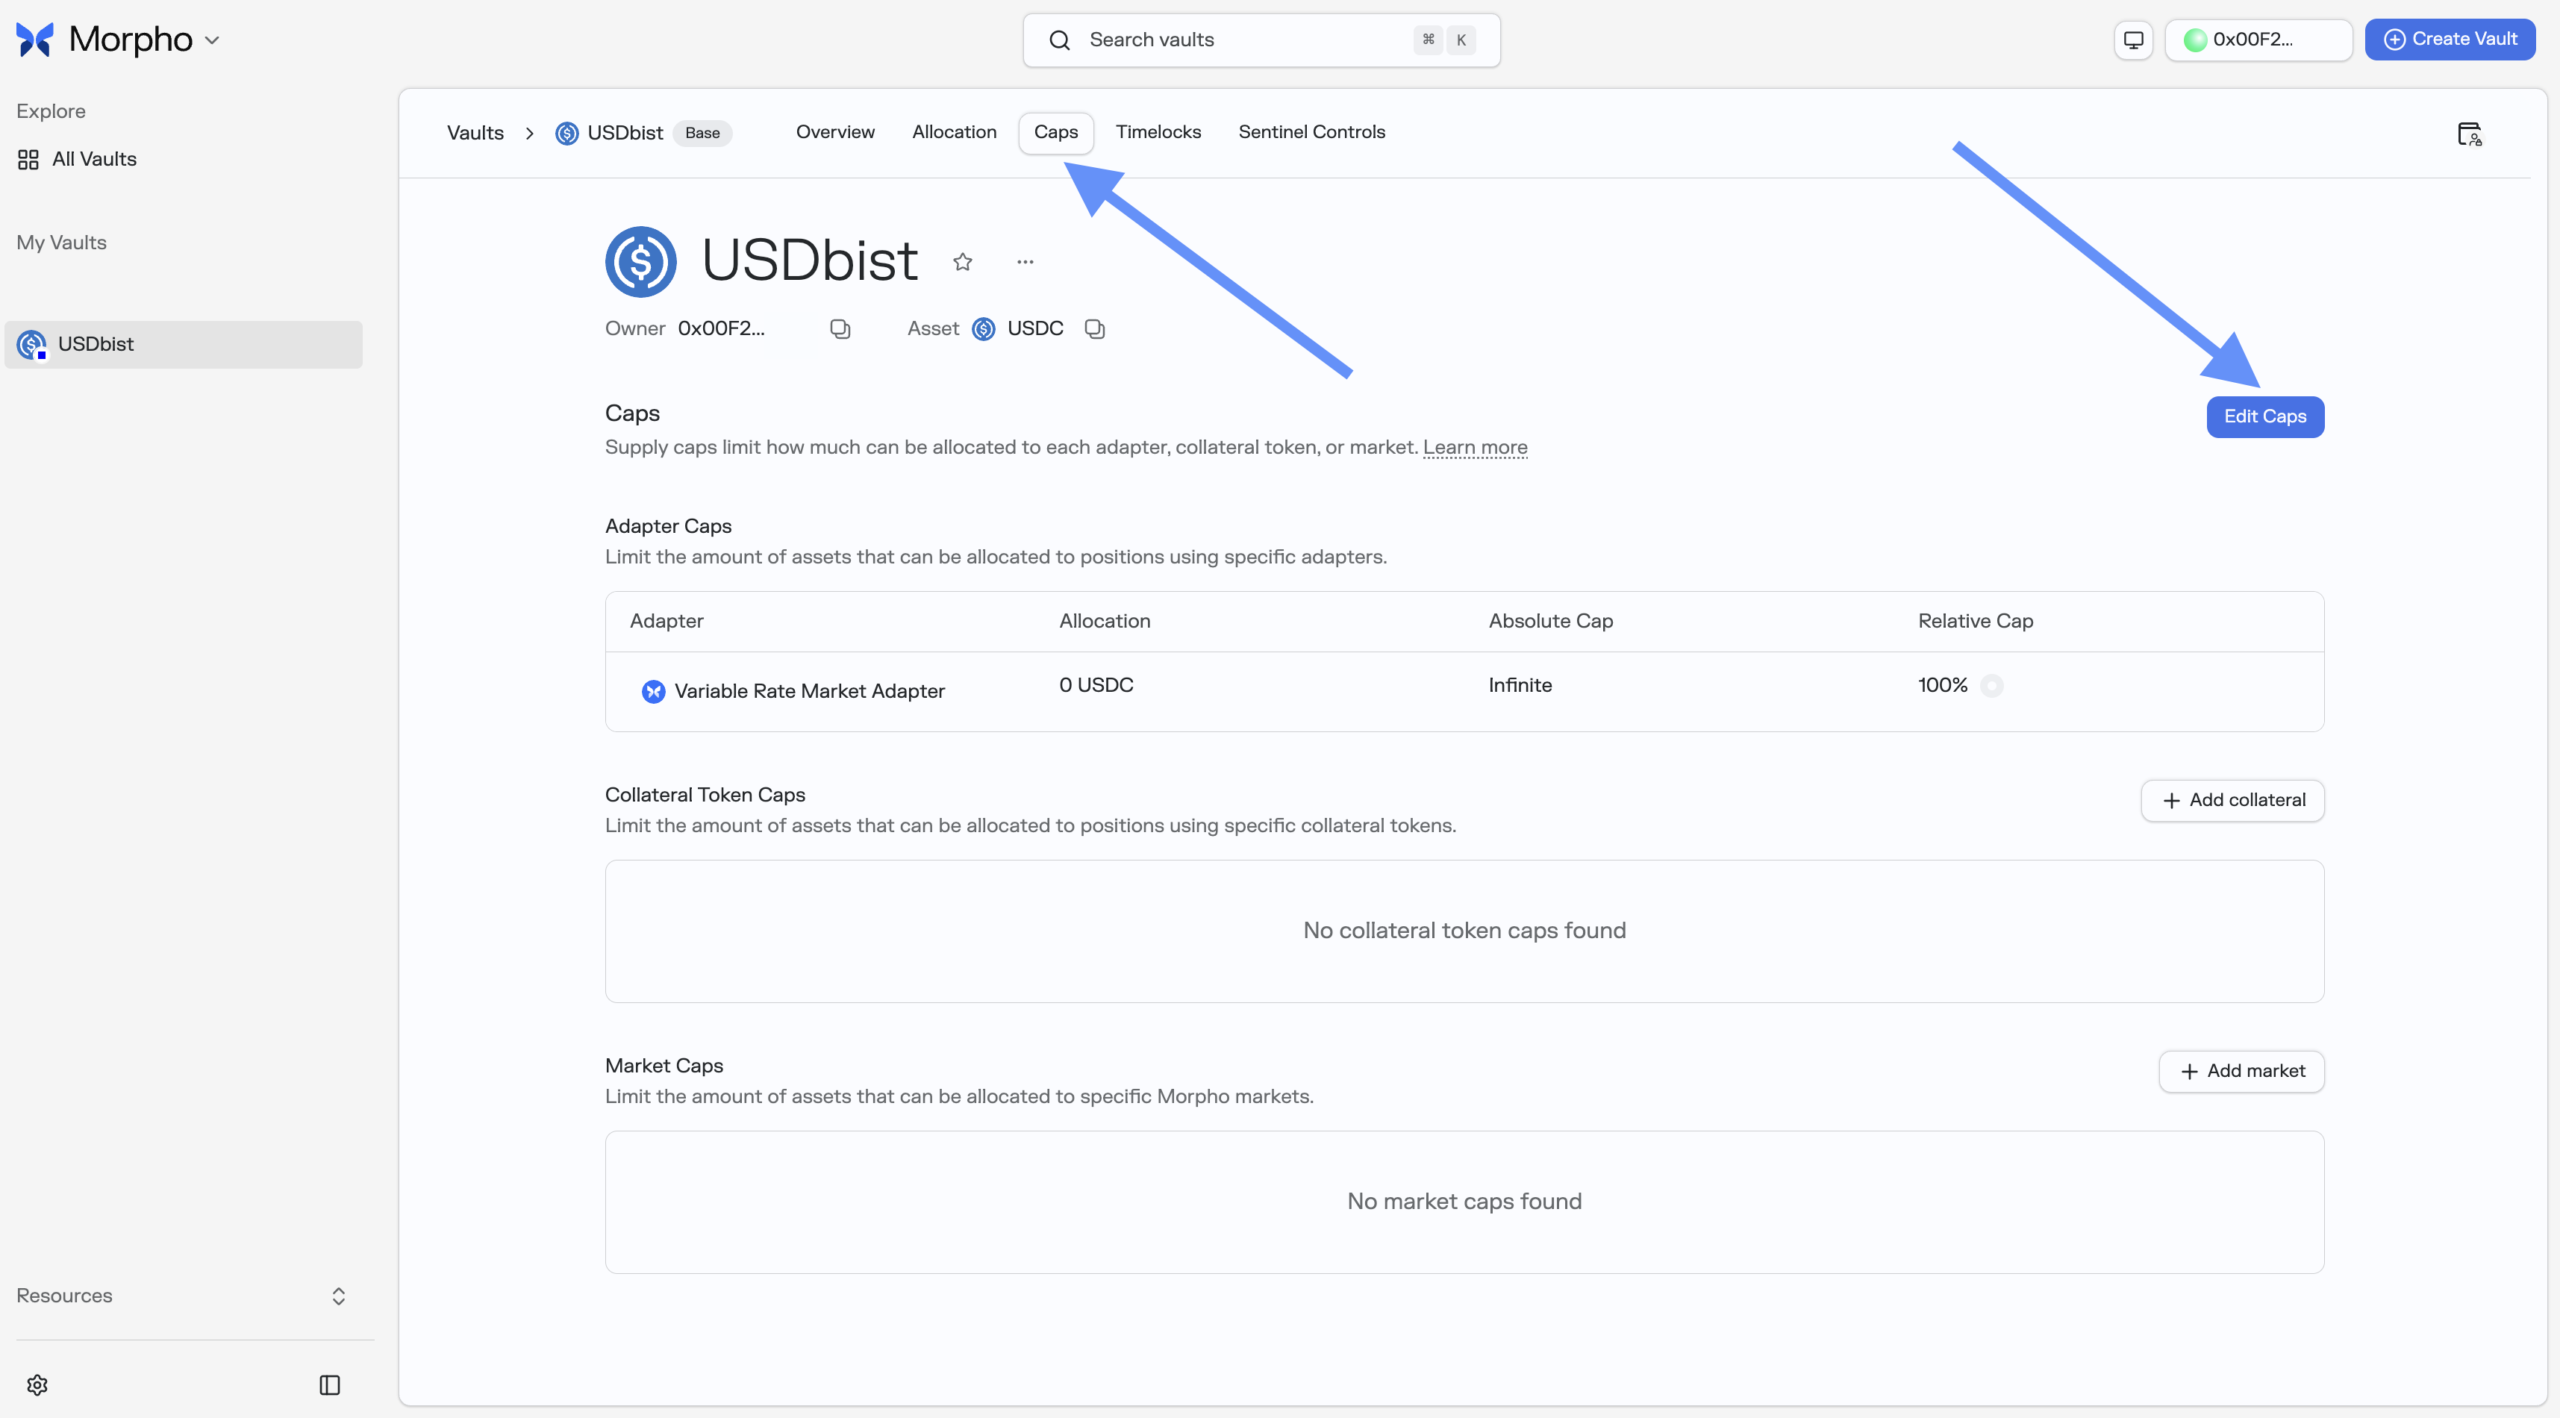
Current USDC supply rates on Morpho Blue: 6.1–8.9% APY depending on market and collateral type. The higher rates reflect higher utilization in specific markets (ETH collateral USDC borrow is the most active) rather than higher smart contract risk.
Devcon 8 relevance: Morpho’s cross-chain expansion plans are likely to receive technical detail at Devcon 8. The Morpho team has been an active contributor to the Ethereum L2 ecosystem and presented at prior Devcon editions.
Risk comparison
| Protocol | Smart contract risk | Collateral risk | Oracle risk | Centralization |
|---|---|---|---|---|
| Aave v3 | Low (3+ years, multiple audits) | Low (established collateral types) | Low (Chainlink) | Low |
| Curve | Low (5+ years) | Low (stablecoins) | Medium (Curve oracle) | Low |
| Pendle | Medium (2+ years) | Medium (underlying asset) | Medium | Low |
| Morpho Blue | Medium (2 years) | Varies by market | Low (Chainlink) | Low |
| EigenLayer restaking | High (new, complex) | Medium | Low | Medium |
Understand where the yield actually comes from
An APY is only meaningful when the source of return is identifiable. Lending yield comes from borrowers paying interest. AMM yield comes from trading fees and sometimes token incentives. Staking yield comes from protocol issuance and transaction rewards. Funding-rate strategies earn the spread created by derivatives positioning, while points campaigns rely on the expectation of a future token or reward that may never match the implied valuation.
Separate organic yield from incentives. Organic revenue is paid by users of the service and can persist when token rewards decline. Incentive yield is funded by emissions, treasury subsidies, or temporary campaigns and often falls when the program ends. A headline APY that combines both should be decomposed before comparing it with another protocol.
Also distinguish APR from APY. APR describes a simple annualized rate, while APY assumes rewards are reinvested at a particular frequency. If gas costs or lockups prevent frequent compounding, the realized return may be closer to APR. Variable DeFi rates can move long before a full year passes, so an annualized dashboard number is a snapshot rather than a guaranteed return.
Calculate net yield instead of comparing headline APY
Start with the base rate, then subtract every cost needed to enter, maintain, and exit the position. These costs can include Ethereum gas, bridge fees, swap slippage, vault management fees, performance fees, borrowing interest, hedging costs, and the opportunity cost of a withdrawal delay.
For a $1,000 position, a $25 entry cost and a $25 exit cost consume five percentage points before any protocol risk is considered. The same costs are only 0.5 percentage points on a $10,000 position. This is why an L2 deployment with a slightly lower headline rate can produce a better net result for a smaller depositor than Ethereum mainnet.
Use a simple comparison:
Expected net return = projected rewards + expected fees earned − transaction costs − protocol fees − hedge or borrow costs
Then test a conservative case in which the variable rate falls, token incentives lose value, and exit slippage increases. If the position is unattractive under a modest stress scenario, the displayed APY is probably not adequate compensation for the complexity.
Additional risks hidden behind a single APY
Liquidation risk: Leveraged lending and looping strategies can unwind when collateral falls or borrow rates rise. Galaxy Research’s analysis of Aave leverage shows why the same collateral can support multiple layers of exposure.
Oracle risk: Lending markets and derivatives depend on price feeds. A delayed, manipulated, or thin-market price can trigger incorrect liquidations even if the protocol code performs as designed.
Depeg risk: Stablecoins, liquid-staking tokens, and receipt tokens can trade below their reference value. A pool may continue earning fees while accumulating the weaker asset.
Governance and admin risk: Upgrade keys, guardians, multisigs, parameter changes, and emergency controls can materially change the position. Review who can pause withdrawals, change collateral factors, or upgrade contracts.
Composability risk: A vault may combine several protocols. Failure in the underlying asset, oracle, bridge, lending market, or strategy contract can affect the final receipt token even when the vault itself is not exploited.
A safer deployment process
Verify the contract and network from the protocol’s official documentation before connecting a wallet. Start with a small test deposit, confirm the receipt token appears, and perform a test withdrawal before increasing the position. Record the entry asset, number of units, transaction hash, quoted rate, and all fees so realized performance can be compared with the dashboard APY.
Avoid concentrating all stablecoins or ETH derivatives in one protocol, one collateral type, or one chain. Diversification does not eliminate smart-contract risk, but it can prevent a single oracle failure, depeg, bridge incident, or governance action from affecting the entire allocation.
Before depositing, define the exit conditions. These might include a utilization spike, sustained stablecoin depeg, falling liquidity, an oracle incident, a contract upgrade, or an APY dropping below the minimum acceptable return. Confirm where secondary liquidity exists for PT, LP, or vault tokens and whether exiting before maturity creates a market-price loss.
Finally, verify live rates directly on protocol dashboards. Pendle documentation explains that PT and YT separate principal from future yield, but the market price determines the fixed return available at the moment of purchase. The same principle applies across DeFi: the mechanism may be stable while the quoted opportunity changes continuously.
FAQ
What is the safest high-yield option in Ethereum DeFi in November 2026?
Aave v3 USDC on Base offers 5.8–7.2% with the lowest smart contract risk profile — 3+ years of operation, multiple audits, and the most battle-tested codebase in DeFi lending. It is not the highest yield available but represents the best risk-adjusted option for conservative yield seekers.
Does Devcon 8 change DeFi yields directly?
Not immediately. Devcon announcements affect yields indirectly by influencing TVL flows, developer activity, and protocol roadmap execution timelines. Positive Devcon coverage for a protocol typically increases its TVL in the following weeks, which can compress supply yields as more capital competes for borrower demand.
What is Morpho Blue and how does it differ from Aave?
Morpho Blue is an isolated lending protocol that creates specific markets for collateral/borrow pairs rather than shared liquidity pools. It offers higher rates because utilization in active markets is higher. The trade-off is less liquidity diversification and higher smart contract risk relative to Aave.
Is Pendle safe to use?
Pendle is a 2-year-old protocol with multiple security audits. The primary risks are smart contract risk from the PT/YT split mechanism and the underlying asset risk (stETH depeg, Ethena synthetic risk for sUSDe positions). For conservative users, PT-stETH positions carry the lowest additional risk on top of ETH staking.
Disclaimer: This article is for informational purposes only and does not constitute financial or investment advice. Cryptocurrency and digital asset markets carry significant risk. Always do your own research before making decisions.
Defiliban · Briar Ellington

Briar Ellington
@briar-ellington